
The essential guide to optimising your Capital Allowances claim
Discover the essentials of Capital Allowances and how they can help reduce your tax bill.
The History of Capital Allowances: A Timeline
Capital allowances can help businesses reduce their tax liability on qualifying investments. Discover how the rules have evolved and what businesses need to know to make the most of available relief in 2026.
Land Remediation Relief (LRR): HM Treasury Proposes Major Reforms
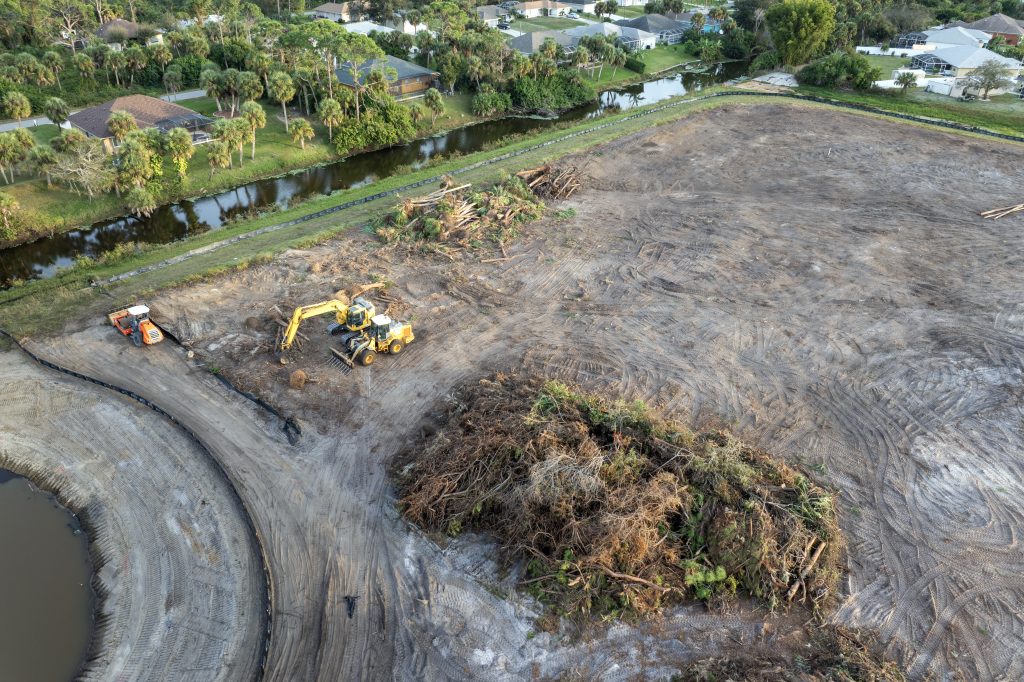
In July 2026, HM Treasury issued a consultation paper detailing structural options to reform Land Remediation Relief (LRR). Governed by Part 14 of the Corporation Tax Act 2009, LRR provides an additional 50% deduction for eligible revenue expenditure (150% total) and a 150% deduction for eligible capital expenditure, with loss-making companies able to claim a 16% cash tax […]
The benefits of using Capital Allowances experts vs. accountants
At Leyton, we completely understand the benefits of using a trusted accountant. That’s why our Capital Allowances experts can work alongside yours, not instead of them. And the benefits of using Capital Allowances experts are very real. Experts can deliver huge savings for your business, especially if you’ve recently finished any large, complex projects like: […]
Leveraging Capital Allowances
In today’s market, supply chains face rising costs, disruption, and ongoing uncertainty. Leveraging the right tax strategies can provide both immediate relief and long-term resilience. We explored how businesses can use Capital Allowances to strengthen their tax position. Benefits of claiming Capital Allowances Short term actions? Retrospective expenditure Long term actions? Current and future expenditure […]
HMRC guidance on Capital Allowances for Real Estate Investment Trusts (REITs)
HMRC’s Investment Funds Manual provides guidance on Capital Allowances for Real Estate Investment Trusts (REITs). The guidance confirms that a claim for first year allowances (FYA) in respect of capital expenditure (e.g. full expensing) and the annual investment allowance (AIA) is permissible but not mandatory. This is different to the position for writing down allowances (WDA), which must be claimed in full where available. How do Capital Allowances impact REIT distribution requirements? The amount of Capital […]
Plant vs. premises: Court of Appeal decision in Urenco Chemplants Limited & Anor vs. HMRC
The debate over what constitutes plant versus premises for Capital Allowances received some clarity after a previous Court of Appeal (CoA) ruling. The CoA was asked to consider this case in order to determine which elements of the construction of the nuclear decommissioning facility qualify for plant and machinery allowances (PMAs). The verdict was predominantly […]
What is the Annual Investment Allowance (AIA)?
The Annual Investment Allowance (AIA) is part of the UK’s Capital Allowances regime designed to encourage business growth by allowing companies to deduct 100% of the cost of qualifying assets from their taxable profits in the year of purchase. The maximum amount of qualifying expenditure eligible for this 100% first-year deduction is strictly capped at £1 million […]
Capital Allowances on second-hand property purchases
In this article, we explain the rules around claiming Capital Allowances on second-hand property purchases while also offering our advice for both buyers and sellers. When you can claim Capital Allowances on second-hand buildings When buying a second-hand commercial building with fixtures on which Capital Allowances have been, or could have been, claimed by the […]
Court of Appeal confirms pre-construction development costs can qualify for Capital Allowances
A recent Court of Appeal decision in Orsted West of Duddon Sands (UK) Ltd and others v HMRC [2025] EWCA Civ 279 provided clarity on the Capital Allowances treatment of pre-construction development costs, such as environmental assessments and engineering studies involved in developing offshore windfarms. The appellant companies were members of the same corporate group […]